Millions of Americans struggling with student loan payments could be bringing their frustrations to the ballot boxes. Amid the Trump administration’s many changes affecting the Department of Education (DOE), surging default rates and the prospect of wage garnishment could generate a larger affordability issue ahead of the November 3 midterm elections. As of June 30, 9.3 million federal student loan borrowers were in default, while another 1.5 million were in late-stage delinquency, according to Federal Student Aid.
And around $234 billion, or roughly 14 percent of the nation's $1.7 trillion student debt load, was in default. The DOE is also working with the Treasury Department as the Trump administration prepares to step up collection efforts against borrowers who have defaulted. Those efforts could eventually include administrative wage garnishment and even the interception of federal tax refunds.
A recent Student Debt Crisis Center survey found 88 percent of respondents said their student loan experience would affect their midterm vote, while 71 percent said it would have a significant influence. President Donald Trump's second term has brought major changes across the board to the federal student loan system at the same time borrowers are confronting broader cost-of-living pressures dominating the 2026 elections. Student debt affects a large voting bloc, as roughly one in six American adults has federal student loan debt.
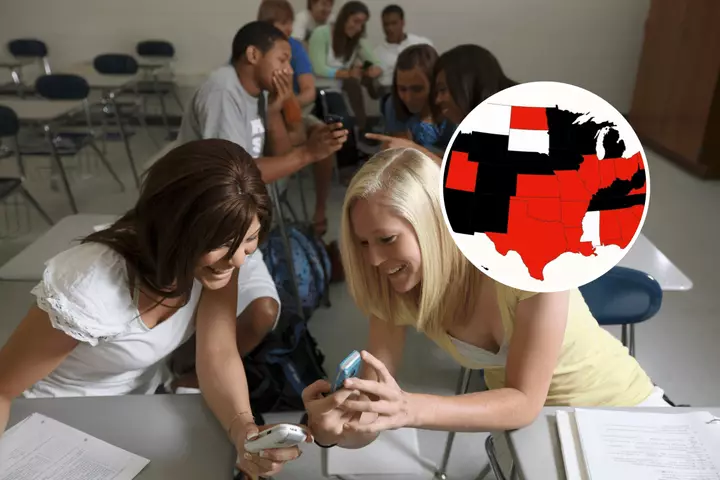
The national rate of borrowers at least 60 days behind on federal or private student loan payments stood at 15.8 percent in August, according to an Urban Institute study. Texas and Ohio, which are gearing up for competitive Senate races, were above the national average. Nine House battleground districts identified by the Cook Political Report also had delinquency rates exceeding the nationwide level, including Texas' 34th Congressional District at about 28 percent and North Carolina's 1st Congressional District at approximately 25 percent.
New Education Department data showed 400,000 additional borrowers had entered default by June, bringing the overall number above 9 million. Federal loans generally enter default after 270 days of missed payments. But at the same time, borrowers are navigating changes to their repayment options.
The Center for American Progress estimated that borrowers switching from the Biden-era SAVE plan to the new Repayment Assistance Plan could see payments rise by an average of $2,163 annually. The Trump administration has also been reportedly preparing to intensify collection efforts against defaulted borrowers, with the Education Department and Treasury working toward using private collection agencies. Legally, that could mean garnishing up to 15 percent of a defaulted borrower's wages and even intercepting federal tax refunds or offsetting certain federal benefits.
Extract — continue reading at the source.